To invest, it is not enough to try to get the future right
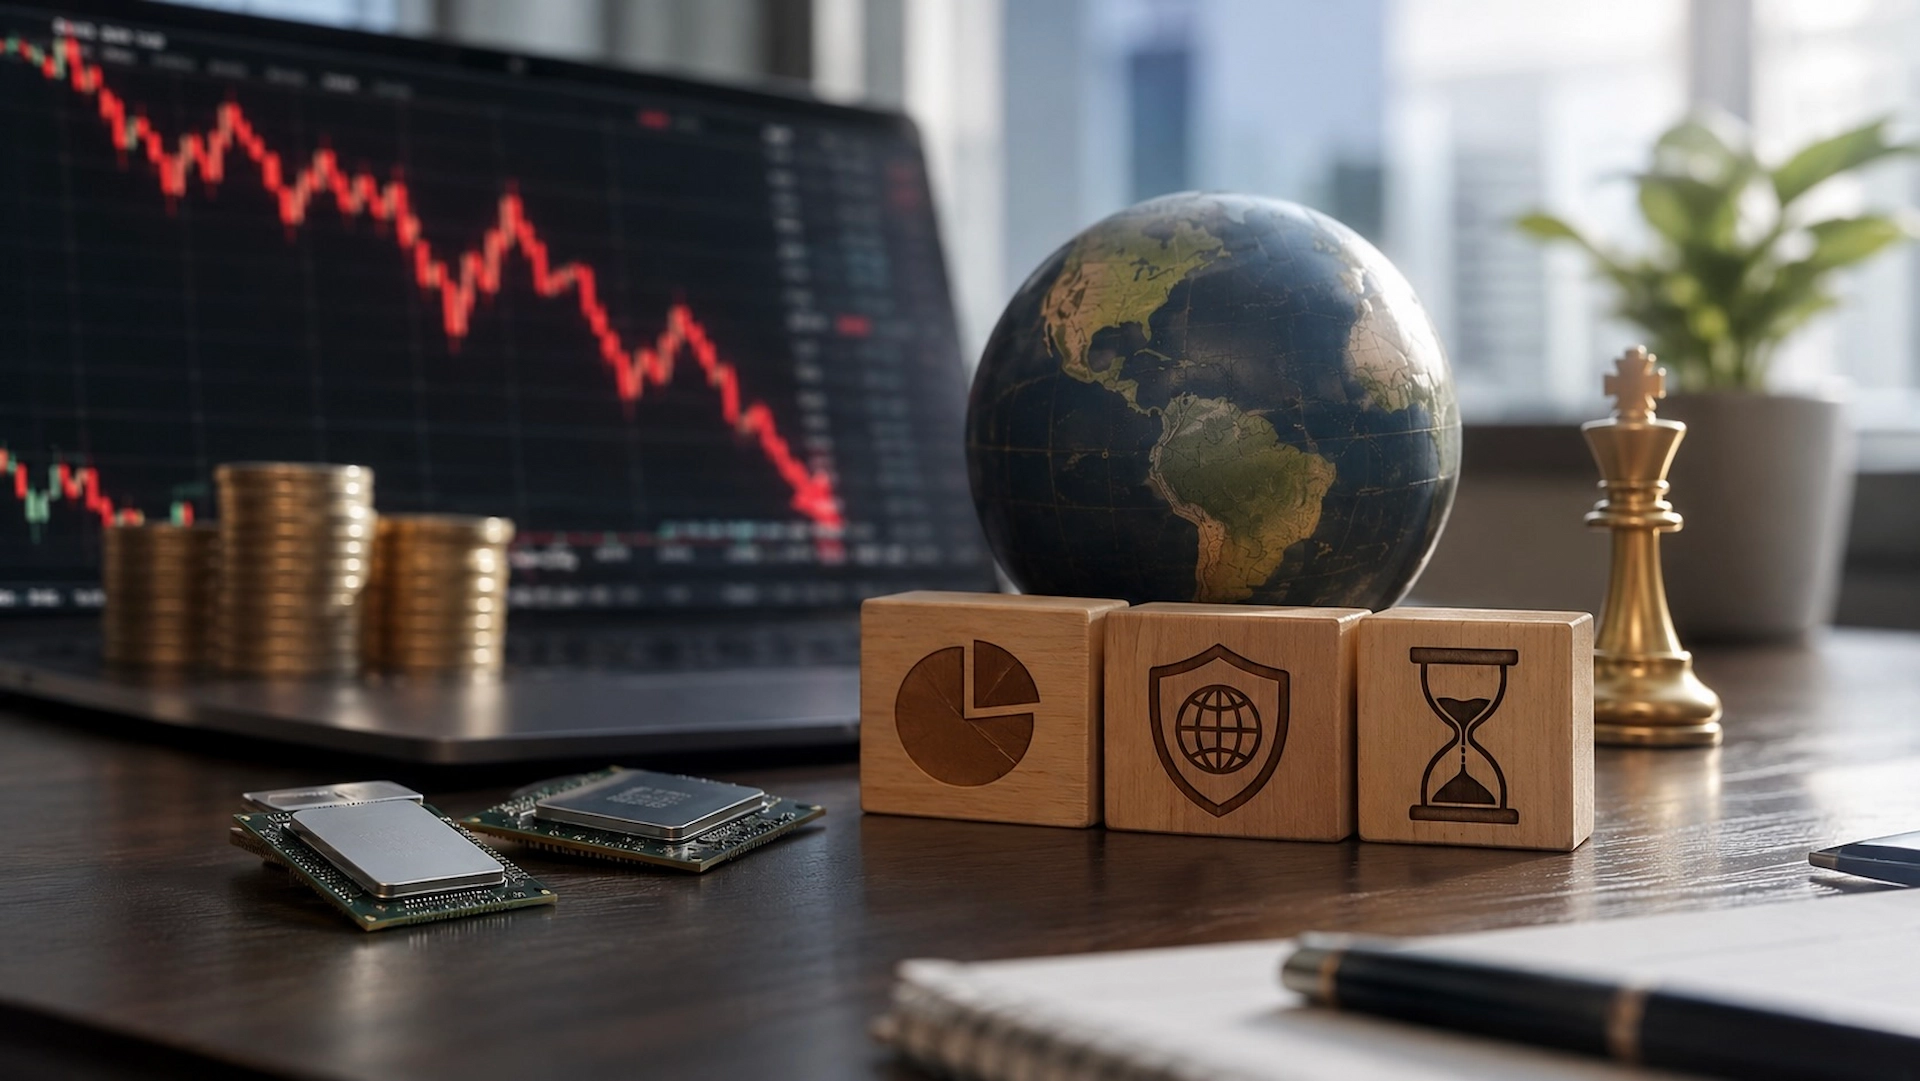
Investors are wrong when they give excessive weight to guessing what is going to happen in the short term and this is what is happening with many companies linked to Artificial Intelligence (AI) and the technology sector in general
In fact, there are few who still doubt the goodness of Artificial Intelligence (AI) as a financial investment and its beneficial consequences, on balance, for the growth of the global economy. But, situations such as the one experienced in recent days with the sharp fall in the shares of the AI and semiconductor sectors that extended from the United States to Asia (South Korea’s KOSPI recorded its worst week since October 2008), may cause many investors to rethink the weights of each type and subtype of asset in their portfolios.
To top off the tech upsets, CoreWeabe (an American cloud infrastructure provider company specializing in AI and backed by Nvidia), lost more than a third of its value in just a few sessions. This was due to the crisis of confidence in the market in the face of its high debt and the rising cost of it.
Underlying all of the above are concerns about the financing of AI infrastructure and competitive risks from China and serve as a reminder that a positive outlook for a listed company, a sector or a market in general does not mean that investors can overlook concentration risk and the need to maintain a time horizon aligned with the risks assumed.
Some rules for investment efficiency and peace of mind in this troubled environment
In view of the above, the first thing that an investor who wants to build a portfolio must take into account is to accept that, to a large extent, what they pay today for an investment, especially if it is in equities, is already largely reflecting what the market believes will happen in the future. This rule is especially applicable to many companies in the technology sector.
Keeping the weight of equities and risk assets in general well adapted to the risk profile desired by an investor is perhaps the investment principle that, although obvious, is not advisable to remember.
In the same way, it is necessary to mention that high diversification offers intrinsic protection against bear markets. As an illustration, he recalled an analysis by UBS that since 1945, during bear markets, the American S&P 500 index fell by an average of 34.5% and spent 39 months «undervalued», while a portfolio of 60% equities/40% fixed income, the minimum diversification required, lost on average in the same periods only 20% and registered a new maximum within the following 30 months.
In short, concentrated portfolios can make results disproportionately dependent on specific companies. Diversification across assets, regions, sectors, and investment styles reduces company-specific risk, while maintaining exposure to future market gains.
Finally, I will include in this brief reminder of some investment principles the convenience of having potential «geopolitical hedges», since it is also more than proven that, without being without risk, they constitute a strategy that can compensate for the falls of other assets: I am referring to exposure to commodities in general, also listed companies whose income statements are favoured by an increase in energy costs and have positions that benefit, directly or indirectly, from a strong dollar. Exercises such as the present one clearly reveal all this.
There’s still a lot of AI left for the markets
Another guideline to be applied that is especially good to remember in this column is to have the winners of global growth in your portfolio. These will end up bearing fruit, with due investor patience, in the form of a rise in their prices because they are the backbone of humanity’s growth. The fall in share prices explained here does not undermine, by any means, the favourable structural outlook for the AI sector.
I expect the positive stock market trend to continue over the next few months as resilient economic activity, broad-based corporate earnings growth, and robust investment in AI should support markets. Moreover, relatively moderate monetary tightening by central banks should have a limited impact on growth.
However, to conclude this «diary» of recommendations, keep in mind the positions linked to dynamic allocation strategies for stocks, bonds and currencies, usually instrumented via specialized investment funds. In the current year, several of them beat the performance of the most prominent indices and with much less volatility (risk) than these.