Are markets in a danger zone?
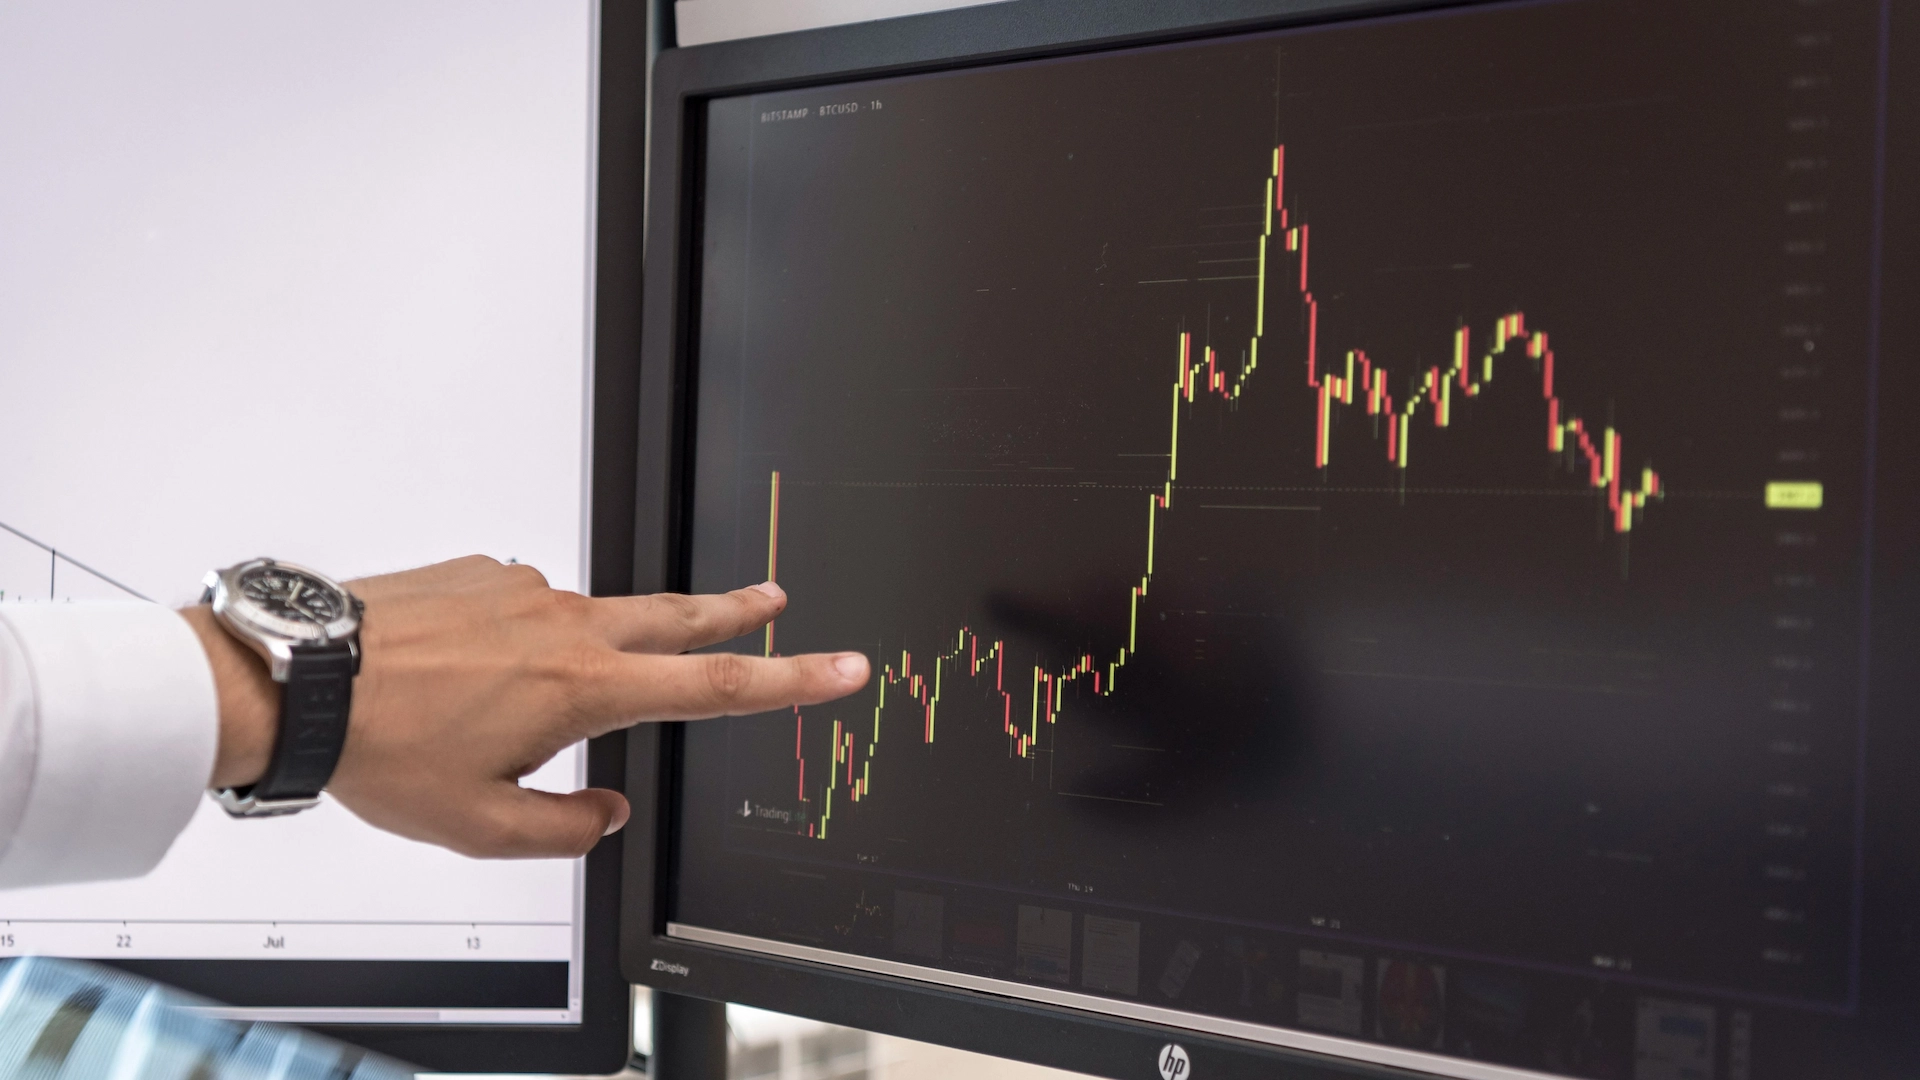
The equity risk premium (ERP), or the additional return that investors demand for investing in stocks instead of in assets considered theoretically risk-free, is currently «missing».
In recent weeks, we’ve seen stock markets frequently reach all-time highs, driven by strong first-quarter results and renewed investor interest in artificial intelligence ( AI ) investments, most notably in the semiconductor sector. However, while investor demand for certain stocks seems almost insatiable, as demonstrated by SpaceX’s IPO last Friday, equities may appear less attractive compared to bonds, much like they did during the dot-com bubble at the beginning of the millennium.
Historical overview
For most of the past two decades, that risk premium has been positive, rewarding investors for taking on equity risk. Today, the S&P 500’s earnings yield—the percentage of earnings generated by companies relative to their stock market valuations—is roughly equal to, or in some calculations lower than, the yield on U.S. Treasury bonds. This, according to a report by analyst Neuberger, is a situation last seen at the height of the dot-com bubble.
A warning sign that should be taken with caution.
As the aforementioned analyst points out, before drawing conclusions, it’s worth issuing a caveat about the indicator itself. The ERP, as it’s typically measured, can offer a somewhat imperfect comparison . Technically, the yield offered by a bond indicates exactly what will be received until the bond’s maturity (barring default by the issuer). In contrast, equity cash flows are uncertain and, to a large extent, grow over time. A stock accumulating profits at 10% annually is a different asset than a bond offering a 4% yield, even if a current snapshot might make them appear equivalent.
That said, warning signs like this deserve attention . The last time ERP fell to such a low level—in the late 1990s—this situation persisted for longer than most analysts expected before abruptly reversing.
The lesson from that episode can be summarized as follows: when investment concentration is high—that is, when a single theme dominates the market (as is the case today with AI)—and the gap between what is paid and potential gain narrows, the portfolio becomes increasingly vulnerable to corrections when growth falls short of expectations. It’s that simple.
Believer in AI but with proper diversification
In recent quarters, AI has driven most of the stock market’s returns and justifies high valuations, and I believe it has significant room for growth and could continue to boost equity markets. However, investors who over-focus their investments on this theme are taking on a risk that is largely unnecessary (since the market doesn’t adequately compensate for it), as diversification can mitigate this risk without sacrificing potential returns.
To begin with, fixed income currently offers attractive absolute returns and has recovered much of its diversifying value. Beyond fixed income, the wide range of equity alternatives also allows for increased expected returns by making sound selections without taking on more risk than desired. Currently, it would be advantageous to take advantage of the US small and medium-sized enterprise (SME) market segment, which boasts attractive valuations and clear upside potential, as well as some emerging market stock exchanges (especially in Asia) . Money market assets and investments linked to the real economy ( private equity and private debt ) would complete the diversification effect by adjusting a portfolio’s return potential to its assumed risk level in the most efficient way possible.
Suddenly, the stock market may find itself at a crossroads
As I indicate in the subtitle, phenomena like the AI boom we are currently experiencing and the supercycle it entails may place us at a crossroads, given that profits may continue to surprise, but not as much as stock market valuations would suggest. The idea that the market will only move in one direction (upward) has always been flawed.
Therefore, by recognizing where we are in the economic cycle , taking into consideration the signal sent by the stock market risk premium , even accepting its limitations, and building truly diversified portfolios , we can be confident in achieving stability in valuation and favorable returns in our investment portfolio for the coming quarters.